

Venture Capital: How Investing in Startups Works
Slush, a conference for startups and investors. Jussi Hellstén / Slush, CC BY-SA 2.5
Venture capital is investment in privately held companies with the potential for rapid growth. An investor provides capital in exchange for an ownership stake or the right to receive one in the future. The aim is to sell that stake at a higher price as the company grows. But the business may struggle to find customers, run out of funding or shut down.
A young company needs money to develop its product, build a team and enter the market. Investors gain an opportunity to participate in its growth before its shares become publicly traded. Years may pass between investing and selling. Here is how these deals work, why a startup's valuation differs from an investor's return, and what to check before buying.
What venture capital means
In finance, venture capital refers both to investment in fast-growing companies and to the industry that finances them. A venture is a business undertaking involving risk. Uncertainty begins with the business itself. A team may still be testing whether customers need its product, how much they will pay and whether it can serve a large market.
Venture investors look for companies capable of substantially increasing sales and value. These are often developers of software, medical technology, new equipment or other products that can reach many customers. Opening another small coffee shop does not, by itself, make a business a venture capital opportunity. What matters is its ability to expand and the economics of that growth.
Funding is available at early and later stages. An early-stage team may have only a prototype. A later-stage company may have an established product, major customers and substantial revenue. The term “startup” therefore covers companies with very different levels of maturity, capital needs and risks.
Why startups need investors
Development and sales require spending before a business generates enough money to fund its own growth. A medical device developer, for example, needs to build a device, conduct trials and obtain the necessary approvals. A software company may need a team to develop its product and acquire customers.
A loan requires repayment of principal and interest on agreed terms. A young company may lack steady cash flow and sufficient collateral. Selling an ownership stake raises capital without a conventional loan repayment schedule, but reduces the founders' stake and may give investors influence over company decisions.
The parties agree on more than the amount invested. They also discuss what the team should achieve with the money. That might be a product launch, growth in paying customers or entry into a new market. If the money runs out before the company can fund itself, another round will be needed.
Who invests in startups
An angel investor invests their own money. Often an entrepreneur, an angel may also contribute contacts and experience. Several angels can form a syndicate to invest in a deal together.
A venture capital fund pools money from multiple investors and invests it in a portfolio of companies. Its management team selects deals and oversees the investments. The managing partners are known as general partners, or GPs, while the fund's investors are limited partners, or LPs. An LP participates in the fund's performance rather than directly owning a stake in each startup.
A corporate venture investor acts on behalf of a large company. Alongside financial returns, it may be interested in technologies, new products and potential partnerships.
An investor's involvement may include a board seat, help with hiring and introductions to customers. For someone investing a small amount through a fund or a special-purpose vehicle, this influence is usually exercised by the manager rather than by each individual participant.
Connie Loizos, Sarah Guo and Elad Gil at TechCrunch StrictlyVC, January 24, 2024. Photo: Nicole Nico Henderson / TechCrunch, CC BY 2.0.
How funding rounds work
A funding round is a period in which a company raises money from one or more investors on the same or similar terms. Stage labels help describe where the company is in its development.
- Pre-seed and seed. The team tests its idea, builds a product and seeks its first customers. Investment finances that process.
- Series A. The company develops its product and sales based on initial evidence of success. Investors assess whether demand is sustainable and whether successful sales can be repeated.
- Series B and subsequent rounds. Funds may go toward expanding the team, entering new markets, adding production capacity or making acquisitions.
- Later-stage and pre-IPO rounds. The company raises capital at a more mature stage. Preparing for a stock market listing may be one objective, but the label “pre-IPO” does not establish an offering date.
These labels do not carry universal revenue or investment thresholds. A company may raise several seed rounds, skip a conventional stage label or sell the business before an IPO.
Mark Christopher Webster presenting Sayspring at Entrepreneurs Roundtable Accelerator Demo Day, April 2017. Photo: MarkChristopherWebster, CC BY-SA 4.0
What the investor receives
Buying shares gives an investor an ownership interest in a company. The rights attached to that interest depend on the share class and deal documents. Preferred stock may provide priority in the distribution of proceeds when the business is sold. Common stock may carry different terms.
Early-stage deals sometimes use a SAFE, a Simple Agreement for Future Equity. It provides for shares to be issued upon events specified in the agreement. Signing it does not immediately make the investor a shareholder. Under Y Combinator's standard form, a SAFE is not a loan and has no interest or maturity date. Its conversion terms determine how many shares the investor will receive later.
Another instrument is a convertible note. It combines debt terms with the possibility of converting the investment into equity. It should not automatically be treated as equivalent to a SAFE.
When investing through a special-purpose vehicle, or SPV, an investor may receive an interest in that vehicle, which in turn owns shares in the startup. It is then necessary to understand who controls those shares, what fees apply and how sale proceeds will reach the investor.
Valuation and ownership
Valuation is the value assigned to a business for an agreed transaction. It is different from revenue, profit or cash in the company's accounts. A round involving newly issued shares distinguishes between the pre-money valuation, before the investment, and the post-money valuation, after it.
Consider a hypothetical example with no debt, options or other instruments. A startup is valued at $4 million before the round. A new investor puts in $1 million. The post-money valuation is $5 million, and the investor owns 20%. The calculation is $1 million divided by $5 million.
If the same $1 million is invested at an agreed post-money valuation of $10 million, it buys a 10% stake. Even in the same company, the entry price changes the potential outcome. A business's rapid growth needs to be considered alongside the price being asked for it.
Why ownership gets diluted
Continue with the example of the 20% stake. Later, the company raises another $4 million at a pre-money valuation of $16 million. Its post-money valuation reaches $20 million, and the new investor receives 20%. Together, the existing owners retain 80% of the company.
If the first investor does not buy additional shares, their stake falls from 20% to 16%. This is called dilution. In this example, the investor's share count remains unchanged, but the total number of shares increases.
At a $20 million valuation, the 16% stake has an implied value of $3.2 million. The ownership percentage has fallen while its implied value has risen. The investor has not yet received any money, however. In an actual deal, employee option plans, convertible instruments and the rights of different share classes also affect the outcome.
Pro rata rights, which allow an investor to participate in subsequent rounds in proportion to their stake, can sometimes help maintain their ownership percentage. Exercising them requires additional capital. Whether these rights apply should be checked in the deal documents.
How investors earn returns
Venture investors primarily expect to earn a return by selling their stake. There are several possible routes.
- Acquisition. Another business acquires the startup. Payments to shareholders depend on the deal structure, the company's obligations and the order in which proceeds are distributed.
- Secondary sale. An investor sells shares to another buyer before an IPO. The seller receives the money rather than the company itself. The transaction may require approval from the company or other shareholders.
- IPO. The company offers shares to public investors for the first time. An early shareholder may gain an opportunity to sell, subject to lockups, trading access and other restrictions.
Suppose the company in our example is sold for $30 million, with all proceeds distributed in proportion to ownership and no debt or preferential payments. The first investor's 16% stake would return $4.8 million. On an initial investment of $1 million, that is a 4.8x multiple and a $3.8 million profit, or a 380% gain, before expenses and taxes.
If the investment lasted eight years, the 4.8x multiple covers the entire period. It is not an annual return. Comparing investments requires taking account of investment and payment dates, as well as fees.
Attendees at TechCrunch Disrupt in San Francisco. Archive photo: Kimberly White / Getty Images for TechCrunch, CC BY 2.0.
Why funds build portfolios
Venture investment outcomes are uneven. A company may shut down or return only part of the money invested, while an individual success may deliver a large multiple. Professional investors therefore assess both individual companies and the combination of investments they hold.
A hypothetical portfolio contains ten investments of $10,000 each, totaling $100,000. Six are lost entirely. Three return $10,000 each. The last returns $200,000. Total proceeds are $230,000, or 2.3x the initial investment, before fees and taxes.
This calculation illustrates how a large success can offset losses. There is no way to know in advance whether a portfolio will include such a company. Buying into ten similar startups also leaves shared risks, such as all of them depending on the same market or source of funding.
The risks investors take
Loss of capital. A product may fail to find demand, a technology may fail testing or a team may struggle to manage growth. If the business closes, nothing may remain after creditors have been paid.
A long wait to sell. Private shares do not offer the same ongoing ability to sell as liquid publicly traded securities. Finding a buyer may take years, and the offered price may be below the valuation in the latest funding round.
Dependence on further funding. A company that spends more cash than it generates from operations needs capital reserves. A weak funding market may force it to raise money at a lower valuation, cut spending or abandon expansion plans.
Distribution terms. Different share classes may receive payments in different orders of priority. The sale price of the entire business therefore does not automatically reveal the return on a particular holding.
Limited information. Private companies usually publish less financial information. Investors need to understand what information they will receive after the deal and who can verify the team's claims.
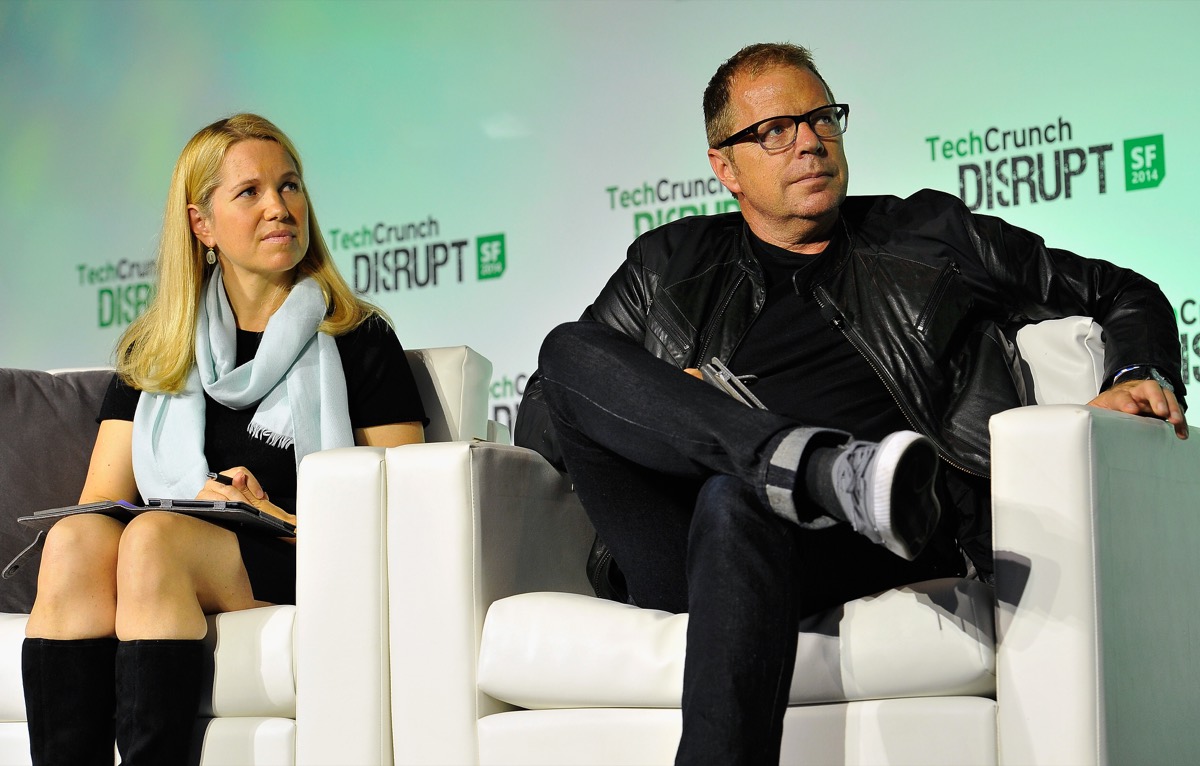
Jessica Livingston and Robert Brunner judging Startup Battlefield, San Francisco, September 9, 2014. Photo: Steve Jennings / Getty Images for TechCrunch, CC BY 2.0
How to assess an opportunity
Start with the product and its customers. Who pays the company, why do they need the product and do they return? Revenue growth is best considered alongside the cost of acquiring customers and serving them. For a hardware company, manufacturing and deliveries matter; for a biotechnology business, research results and development milestones are important.
Next, examine the finances. How much capital remains, how quickly is it being spent and what can the company achieve before its next fundraise? Compare the plan with what the team has already delivered.
Before investing, the asset being purchased and the ownership terms should also be clear:
- Which company or vehicle receives the money and what the investor legally acquires.
- The valuation used for the deal and whether instruments that may later convert into shares have been accounted for.
- The rights attached to the securities and who makes decisions about selling them.
- The fees and expenses that reduce the return.
- The conditions for exiting the investment and what happens if a planned IPO is delayed.
A well-known name on the investor list helps explain the company's funding history, but that investor's terms may differ from those offered to a new buyer. Assess your own entry price and the rights attached to your deal.
Venture capital in a personal portfolio
Years can pass between buying a stake and selling it. During that time, the company will develop its product, find customers and raise further rounds, while the investor waits for an opportunity to sell. Venture investments therefore require capital that will not be needed for several years. The possibility of losing the entire amount also needs to be considered in advance.
The way you invest determines how many decisions you need to make yourself. With a direct investment, you select the company and examine the deal terms. In a fund, the manager does this work and charges a fee. If you invest through a platform or SPV, you need to understand who owns the shares, who decides when to sell them and how the proceeds reach you.
A promising product and a strong team may draw attention to a company, but the investment outcome also depends on the purchase price. The higher the entry valuation, the more the business needs to grow for the investor to earn a return. Alongside the company's plans, it is therefore worth assessing the deal terms and the opportunities to sell the stake later.
